

A supplier invoice should never become a surprise payment. Yet for many growing businesses, accounts payable is handled between sales calls, customer deliveries and month-end pressures. The result can be late payments, duplicated invoices, unclear cash commitments and records that take far too long to reconcile. A clear process turns accounts payable from an administrative burden into a useful source of financial control.
For founders and SMEs, the objective is not simply to pay bills. It is to ensure every legitimate cost is recorded correctly, approved by the right person and paid at the right time. This protects supplier relationships while giving management a realistic picture of cash flow.
What accounts payable means for a growing business
Accounts payable is the money a business owes to suppliers for goods or services already received but not yet paid for. It may include stock purchases, professional fees, rent, software subscriptions, freight charges, marketing costs and contractor invoices.
When an invoice arrives, it creates a liability. Until the payment is made, that amount belongs in the accounts payable balance. Once paid, the liability is cleared and the bank balance is reduced. Simple in principle, but errors tend to arise when invoices are sent to different people, approvals are informal or payment dates are tracked in separate spreadsheets.
For a small company, the owner may initially oversee every payment. As transaction volumes increase, that approach becomes risky. A business needs a process that works consistently even when the founder is travelling, a team member is on leave or several urgent invoices arrive at once.
Why accounts payable affects more than bookkeeping
A well-managed payable process supports day-to-day decision-making. It shows what the business owes in the coming days and weeks, so management can plan funding, customer collections and spending with greater confidence.
It also helps preserve supplier trust. Paying too early can place unnecessary pressure on working capital. Paying late without communication can affect credit terms, delay deliveries or damage a relationship that the business relies on. The best timing depends on the agreed terms, available cash and the importance of the supplier.
Accurate records matter for compliance as well. Hong Kong businesses must maintain proper accounting records that explain transactions and their financial position. Supplier invoices, purchase orders, contracts, payment confirmations and approval records form part of the evidence behind business expenses. Keeping these documents organised makes financial reporting and tax work considerably more straightforward.
There is also a control issue. Duplicate invoices, altered bank details and unauthorised spending often become harder to spot when one person receives, approves and pays every invoice. Separation of responsibilities may be limited in a small business, but basic checks can still be put in place.
The accounts payable process, step by step
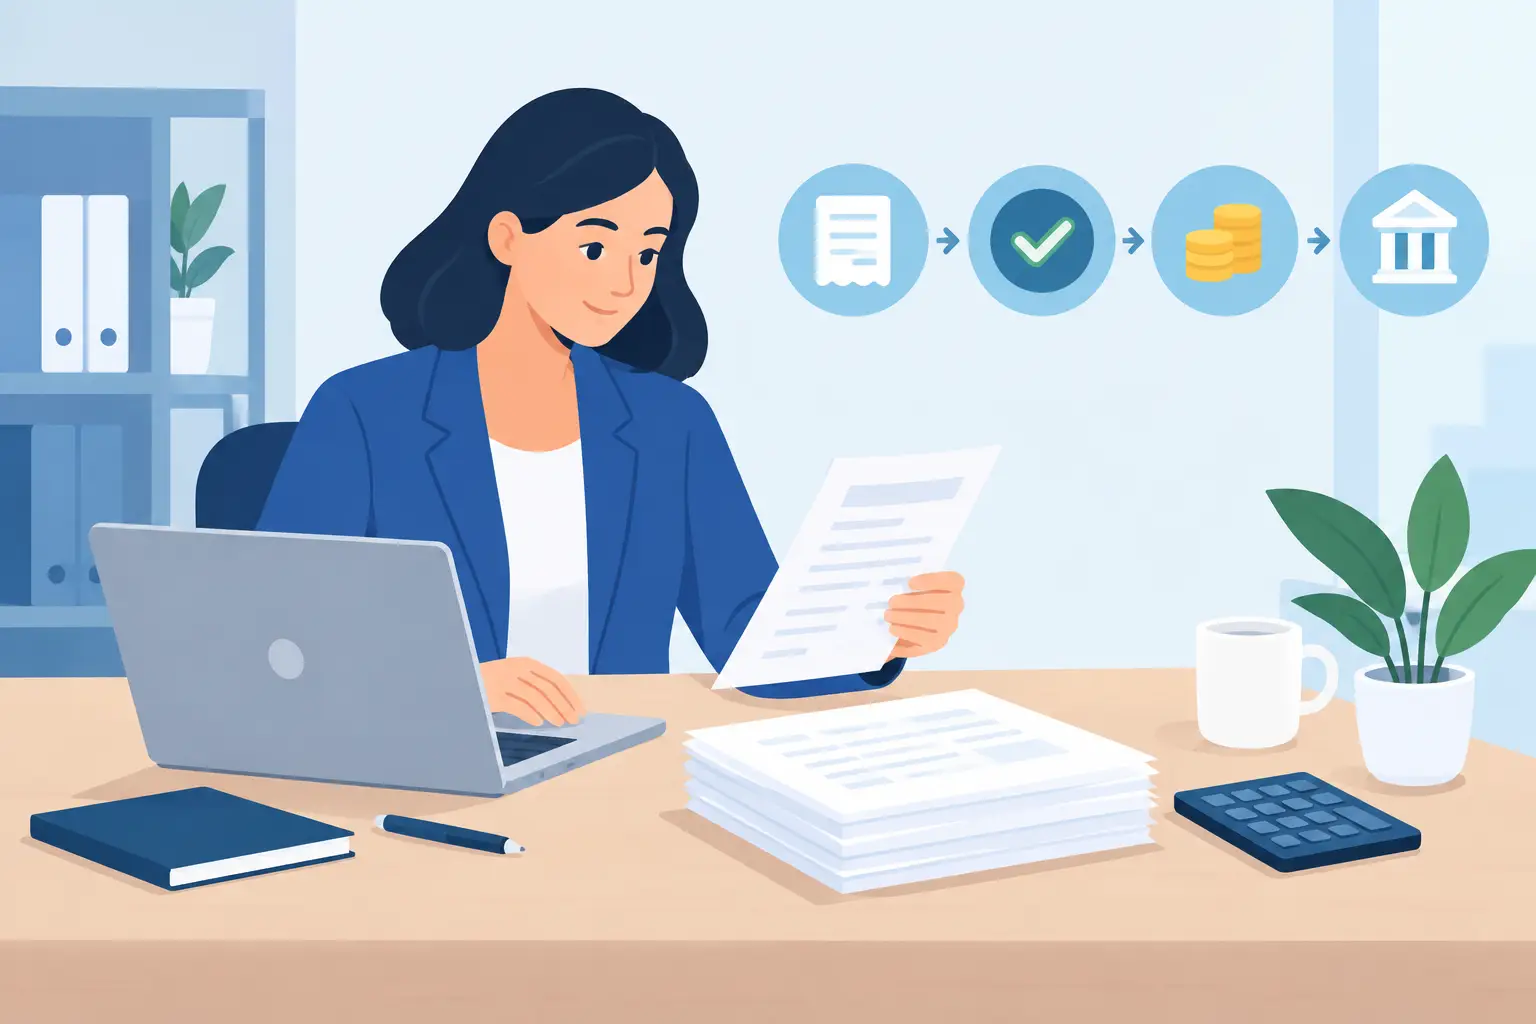
An effective accounts payable process does not need to be complicated. It needs clear ownership, timely records and a reliable approval route.
1. Receive and register invoices promptly
Invoices should be sent to a central business email address or captured through an accounting system, rather than being scattered across personal inboxes and messaging apps. Each invoice should be recorded when received, with the supplier name, invoice number, invoice date, due date, amount, currency and description of the purchase.
Prompt registration gives the business visibility of its obligations before payment is due. It also reduces the chance that an invoice is overlooked until a supplier sends a reminder.
2. Check that the charge is valid
Before an invoice is approved, confirm that the goods or services were ordered and received, and that the charge agrees with the agreed price and terms. For larger or recurring purchases, match the invoice against the purchase order, contract or delivery confirmation.
The level of checking should reflect the risk. A regular monthly software subscription may require a simple confirmation. A significant equipment purchase, overseas supplier payment or unusual one-off fee deserves closer review. A practical process avoids both extremes: paying without evidence and creating so much paperwork that legitimate suppliers wait unnecessarily.
3. Code the expense correctly
Every invoice needs to be allocated to the appropriate expense, asset, project, department or cost centre. This may seem like a minor bookkeeping task, but incorrect coding can distort margins and make management reports less useful.
For example, a payment for inventory should not be treated in the same way as a subscription for an administrative system. Similarly, costs connected to a specific client project may need to be tracked separately from general overheads. Consistent coding helps the business understand where money is being spent and whether costs are rising for a good reason.
4. Obtain documented approval
Approval should come from someone who understands the purchase and has authority to commit company funds. The approval can be recorded in an accounting platform, workflow tool or controlled email process, provided it is clear who approved the payment and when.
A sensible approval limit is often more useful than requiring the founder to approve every small invoice. Routine expenses can be authorised by an appropriate manager, while higher-value, unusual or non-budgeted costs are escalated. This keeps payments moving without weakening oversight.
5. Schedule payment against due dates and cash needs
Payment runs should be planned rather than made reactively throughout the week. Reviewing upcoming due dates once or twice weekly gives management time to check available funds and resolve invoice queries before they become overdue.
Paying on the contractual due date is generally a sound approach. Some suppliers offer an early-payment discount that may be worthwhile, while others have flexible terms that can support cash flow. The decision should be deliberate and recorded, not based on which invoice happens to be noticed first.
For overseas payments, consider bank charges, exchange-rate movements and the beneficiary details carefully. A small error in account information can lead to delays that are time-consuming to correct.
6. Reconcile payments and retain evidence
After a payment is released, the invoice should be marked as paid and matched to the bank transaction. Payment confirmation should be retained with the invoice and approval evidence. This closes the loop and prevents the same invoice from being paid again.
Regular reconciliation also identifies issues early, such as a payment that has failed, a supplier credit that was not applied or a bank charge recorded incorrectly. Leaving this work until year-end creates avoidable pressure and makes errors more difficult to trace.
Controls that suit smaller teams
Smaller businesses may not have a dedicated finance department, but they can still create meaningful safeguards. The key is to design controls that are proportionate to the size and pace of the business.
Supplier bank detail changes should always be verified using a trusted contact method, not only through the email requesting the change. New suppliers should be checked before their first payment, particularly where the amount is material. Bank access should be limited to authorised users, and payment preparation should be separated from final release where possible.
It is also wise to review the supplier master list periodically. Remove duplicate records, inactive suppliers and outdated contact details. When several versions of the same supplier exist in a system, duplicate payments become more likely.
A monthly aged payables report is especially valuable. It shows outstanding invoices by supplier and how long they have been unpaid. Management can use it to identify approaching due dates, investigate old balances and forecast short-term cash requirements. It should be read alongside expected customer receipts, not in isolation.
When outsourced support is the practical choice
Managing accounts payable internally may work well when invoices are few, responsibilities are clear and the business has experienced finance staff. It becomes less efficient when founders spend too much time chasing documents, inputting invoices or responding to supplier queries.
Outsourced accounts payable support can provide a structured process without the cost of building a full in-house function. A specialist team can maintain invoice records, prepare payment schedules, follow agreed approval procedures and keep supporting documents organised. The business retains control over payment authorisation while routine administration is handled consistently.
This arrangement is particularly useful for overseas owners operating a Hong Kong company. Time-zone differences, remote teams and local payment requirements can make ad hoc administration difficult. Having a dependable operational partner helps ensure that invoices are captured, records remain current and deadlines do not depend on one busy decision-maker.
The right setup depends on transaction volume, internal capability and the sensitivity of payments. Some businesses only need bookkeeping support and monthly reporting. Others need a more managed service that coordinates the full invoice-to-payment workflow. Gee Kay Systems & Accounting Limited can help businesses establish processes that fit their operating model while keeping financial records clear and manageable.
Build a process before the volume arrives
Accounts payable rarely causes trouble because of one invoice. Problems develop when a business grows faster than its financial processes. Establishing a central invoice channel, clear approval limits, regular payment reviews and organised records gives owners more control over cash without pulling attention away from growth.
A process that is simple enough to follow every week is usually more valuable than a complex policy nobody uses. Start with the next supplier invoice, record it properly, approve it clearly and make payment a planned business decision.