

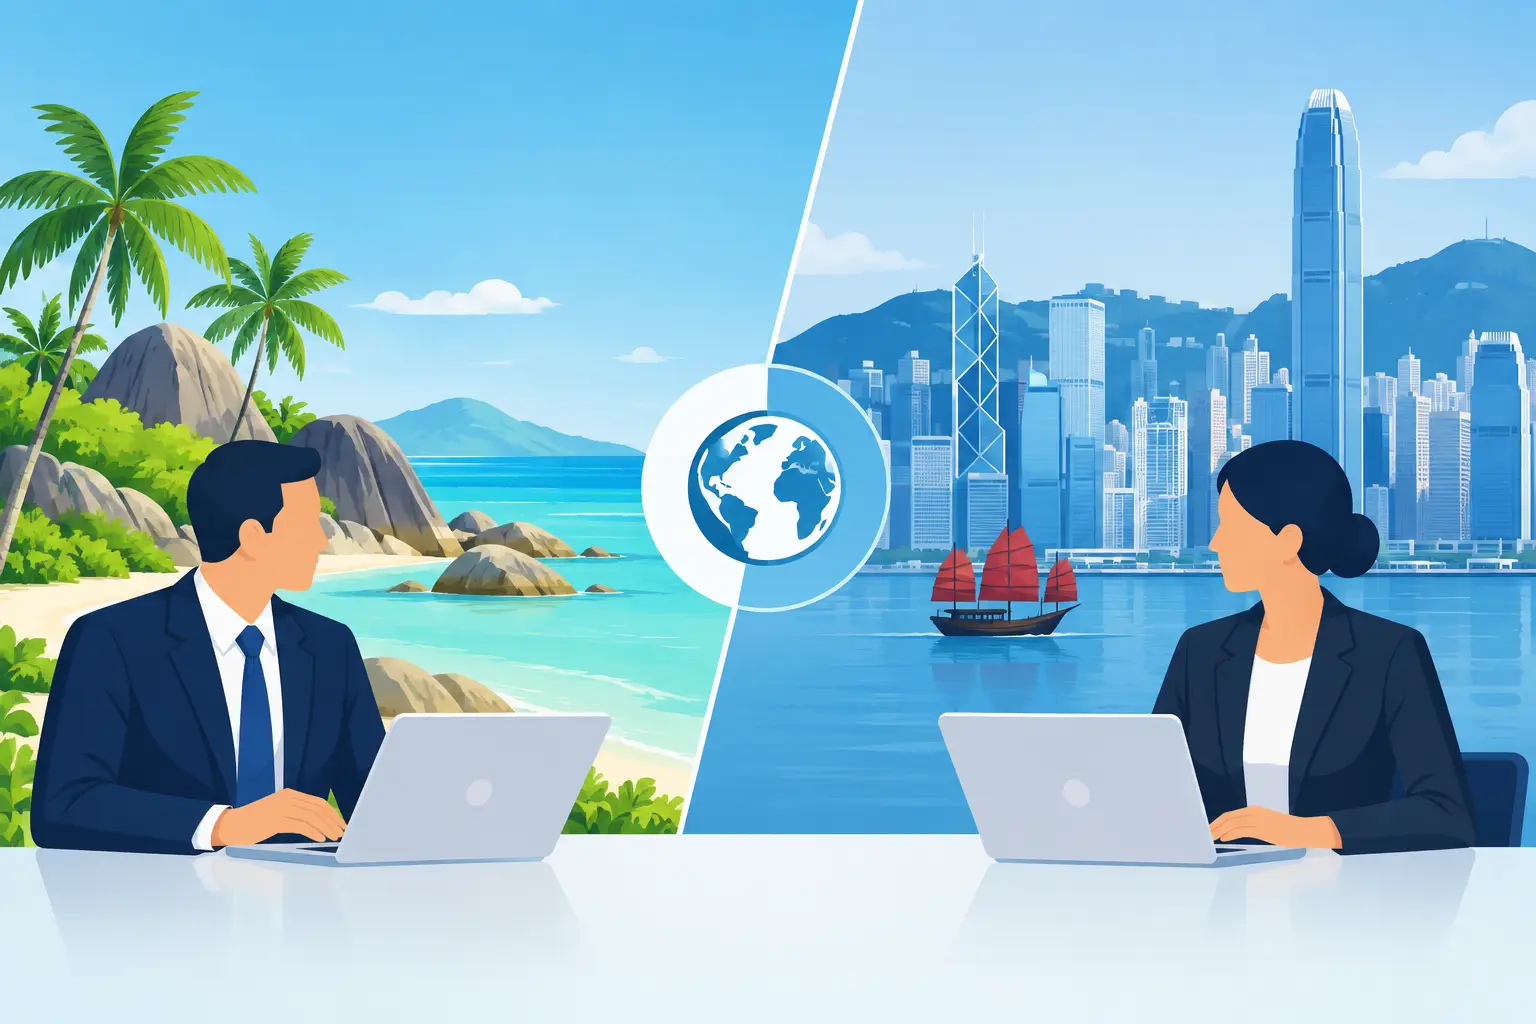
A Seychelles company vs Hong Kong company comparison is not simply a choice between two incorporation fees. It determines where your business is perceived to operate, how easily it can deal with banks and counterparties, and how much ongoing administration your founders will need to manage. The right answer depends on the commercial reality of your business, not just the headline tax position.
For a founder selling internationally, holding investments, or operating a trading business, both structures can have a legitimate role. However, they are designed for different purposes. Hong Kong is generally chosen for an active business presence in Asia. Seychelles is more commonly considered for offshore holding, international ownership structures, or activities with limited connection to the place of incorporation.
Seychelles company vs Hong Kong company: the core difference
A Hong Kong private limited company is often suitable where the business will trade, employ people, contract with suppliers, maintain a regional base, or build credibility with customers and financial institutions. It is a recognised commercial vehicle with a clear statutory framework, but it comes with regular filing, record-keeping and company secretarial responsibilities.
A Seychelles Business Company is typically used as an offshore entity. It may offer a comparatively simple corporate structure and can be useful where owners need an international holding vehicle or a company that sits outside their operating markets. Yet simplicity at incorporation should not be mistaken for an absence of obligations. Seychelles companies still require a registered agent, annual government fees, proper records and compliance with beneficial ownership and economic substance rules where applicable.
The practical distinction is this: Hong Kong is normally built for visible, active commerce, while Seychelles is generally used where the company has a narrower offshore purpose. Trying to use an offshore company for a business that is clearly managed and operated elsewhere can create unnecessary tax, banking and compliance questions.
Tax treatment follows facts, not incorporation alone
Tax is usually the first issue founders raise, but it should be assessed carefully. A Hong Kong company is subject to Hong Kong’s territorial tax system. Broadly, profits that arise in or are derived from Hong Kong may be taxable, while profits claimed as offshore must meet the relevant conditions. An offshore claim is not automatic simply because customers or suppliers are located outside Hong Kong.
For corporations, Hong Kong’s two-tiered profits tax rates are generally 8.25% on the first HK$2 million of assessable profits and 16.5% on the remaining assessable profits. Whether a business is taxable depends on where profit-generating activities are carried out, including where contracts are negotiated, where management decisions are made and how the business is operated.
A Seychelles company may benefit from its own local tax framework where it earns income outside Seychelles, depending on its activities and current legislation. That does not mean its profits are tax-free in every circumstance. The owners’ country of tax residence, the location of management and control, the place where work is performed, and any controlled foreign company rules can all affect the outcome.
For this reason, an offshore structure should never be selected on the assumption that tax can be removed from the picture. Good structuring begins with a clear map of people, contracts, decision-making and revenue, then aligns the company arrangement with those facts.
Compliance and administration are materially different
Hong Kong companies need disciplined annual administration. They must keep statutory registers and accounting records, submit annual returns, maintain a company secretary and registered office, and meet ongoing tax filing requirements. A significant controllers register must also be kept, with a designated representative available to assist authorised authorities when required.
These duties are manageable when they are handled consistently. The challenge for many entrepreneurs is that deadlines, financial records and corporate changes can become fragmented as the business grows. A professional service provider can take responsibility for the routine process, coordinate bookkeeping and filings, and give founders one dependable point of contact.
Seychelles companies have a different compliance profile. They require a Seychelles registered agent and registered office, annual renewal and maintenance of prescribed records. Depending on the entity’s activities, it may also need to meet economic substance requirements or make relevant notifications. Beneficial ownership information is not a matter to be ignored simply because the company is offshore.
Neither jurisdiction should be seen as a “set and forget” solution. Hong Kong tends to involve more visible operational compliance, while Seychelles calls for careful attention to offshore substance, records and the continuing suitability of the structure.
Banking, payments and commercial credibility
For many businesses, banking is the point at which the theoretical benefits of a structure meet commercial reality. Financial institutions conduct detailed due diligence on company ownership, source of funds, expected transactions, customers and the genuine reason for the chosen jurisdiction. A clear business model and complete supporting documents matter more than a low-cost incorporation package.
A Hong Kong company can be more familiar to Asian suppliers, clients, payment providers and banks, particularly when the company has a credible trading or services profile. This does not guarantee account approval, but it can support a straightforward explanation of why the entity exists and where it operates.
A Seychelles company may face closer questioning, especially if the business has no obvious offshore purpose or if the company intends to process payments for higher-risk sectors. Some counterparties may also have internal policies that make them less willing to contract with offshore entities. That can lead to slower onboarding, more document requests or a need to use alternative payment arrangements.
This is not a reason to rule out Seychelles automatically. It is a reason to consider banking and counterparty acceptance before incorporation, rather than after the business has already signed contracts.
When a Hong Kong company is likely to fit better
A Hong Kong company is commonly the stronger choice when you are building an active business that needs to look and operate like a conventional trading, consulting, technology or services company. It is particularly relevant where founders are based in Hong Kong, management decisions are made there, or the company will work closely with Asian customers and suppliers.
It is also usually the more practical option when you expect regular invoicing, staff or contractors, local operational expenditure, external investors, or a long-term regional presence. The ongoing obligations are greater than a basic offshore incorporation, but they create a more structured foundation for growth.
Founders should not treat administration as a distraction that can be postponed. Accurate bookkeeping, timely corporate filings and well-organised financial records make it easier to understand performance, respond to bank requests and make confident decisions as the company expands.
When a Seychelles company may be appropriate
A Seychelles company may be suitable where there is a genuine offshore purpose. Examples can include holding shares in overseas businesses, holding certain international investments, or owning assets within a properly advised cross-border structure. It can also be considered where owners need a corporate vehicle that is separate from the jurisdiction in which they personally live or conduct particular operations.
The key is substance and purpose. If the company will be managed from another country, have employees elsewhere, or earn income through activities carried out outside Seychelles, the owners must understand the rules that apply in those locations. The incorporation certificate alone does not determine tax residence or regulatory treatment.
A Seychelles entity should therefore be established with a clear record of why it is needed, how it will be managed and what transactions it will conduct. This approach helps reduce future confusion when dealing with financial institutions, professional advisers and business partners.
Choosing the structure without creating future problems
Before deciding, founders should answer a few direct questions. Where will key decisions be made? Where are customers, suppliers and team members located? Will the company need conventional business banking and payment services? Is the entity intended to trade actively, or primarily hold assets? Finally, what are the tax obligations of the owners and the jurisdictions where the business actually operates?
If the answers point to a real Hong Kong business presence, a Hong Kong private limited company is often the clearer and more sustainable choice. If they point to a well-defined offshore holding or international structuring purpose, Seychelles may be worth considering alongside appropriate tax advice.
Gee Kay Systems & Accounting Limited supports founders with the practical side of company formation, company secretarial administration, bookkeeping, tax compliance and ongoing corporate maintenance. The aim is not to push every business towards one jurisdiction, but to make sure the selected structure can be administered properly from day one.
The most useful choice is the one you can explain clearly: to your bank, your customers, your advisers and, most importantly, to yourself as the business develops.